Bank of England expected to raise rates to 4% as millions of homeowners brace for mortgage refinancing squeeze


London, 4 November 2026: The Bank of England is widely expected to raise the Bank Rate from 3.75% to 4% on Thursday, 5 November, in what would be its first increase in more than three years, following a sharp rise in UK inflation.
Annual inflation, as measured by the Consumer Price Index (CPI), rose to 3.5% in September, up from 3.1% in August. Prices for services, including restaurants and hotels, are also rising faster, adding to fears that higher energy costs could trigger further price rises across the economy.
Chancellor John Healey’s recent Budget offered some relief on household energy costs, but higher mortgage repayments threaten to absorb much of that ‘breathing space’. For households already juggling rising bills, the concern is that pension contributions become another casualty of the cost of living crunch.
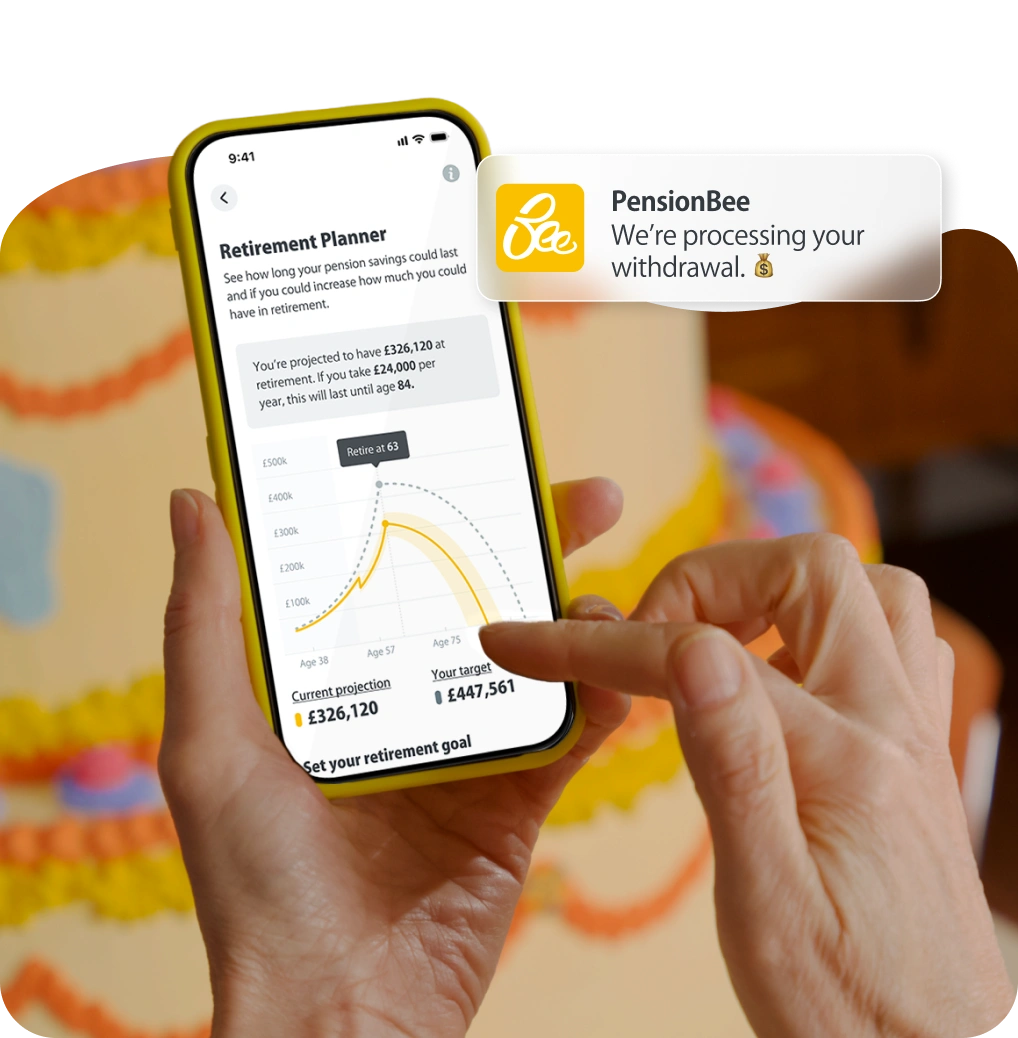
PensionBee research reveals the extent of the squeeze on household finances, with 51% of Britons prioritising everyday living costs over the next year, while only 9% see increasing their pension contributions as a priority.
Maike Currie, VP Personal Finance, PensionBee, comments: “The Bank of England is caught between a rock and a hard place. Inflation is heading in the wrong direction, but raising interest rates risks piling further pressure on households already struggling with the cost of living.
“A quarter-point rise may sound modest, but for millions of mortgage borrowers, the real pain is yet to come. According to UK Finance, more than 2.3 million fixed-rate mortgage deals expire in 2027, and many households will find themselves taking out new deals at much higher rates than they previously enjoyed.
“Borrowers are already making very deliberate decisions, trying to secure mortgage deals early, weighing up whether to fix for two or five years and trying to second-guess where interest rates might go next.
“As homeowners and landlords come off cheaper fixed-rate deals, the pressure on household budgets will only intensify.”
The hidden casualty: pension contributions
Currie added: “When the mortgage is your biggest monthly outgoing and suddenly becomes significantly more expensive, something else has to give. For many households, the temptation will be to reduce or pause pension contributions to free up cash today. But pension saving shouldn’t automatically become the first casualty of rising mortgage costs.
“Pensions are one of the few areas of household finances where your money benefits from both tax relief and, for workplace pensions, employer contributions.
“For example, if you pay £80 into a personal pension, the Government will usually add £20 in basic-rate tax relief, bringing your contribution to £100. Workplace pension savers may also receive money from their employer. That’s a powerful incentive to keep saving, even when household budgets are under pressure.
“Of course, people must prioritise essential bills and avoid falling into expensive debt. But before reducing pension contributions, it's worth reviewing non-essential spending, checking what your employer contributes and understanding the longer-term cost of stopping.”
Did the Budget go far enough?
The Chancellor’s one-off £100 payment for households in Council Tax bands A to D in England, due from January 2027, offers some respite from rising energy bills. But spread across 12 months, that’s just £8.33 a month - a drop in the ocean for homeowners facing hundreds of pounds more in monthly mortgage repayments.
Meanwhile, the Budget’s extension of the temporary VAT cut on electricity until July 2027, alongside plans to abolish gas standing charges and reform electricity standing charges, is welcome. But shifting standing charges onto unit prices won’t necessarily make energy cheaper, and short-term relief is no substitute for permanently reducing the underlying cost of energy.
Currie comments, “Households are being squeezed from all sides, with inflation eroding their spending power while higher mortgage costs swallow more of what’s left. The danger is that families spend the next few years simply trying to keep their heads above water, sacrificing the savings and pension contributions that would otherwise help secure their financial futures.
“The Bank may need to raise rates to bring inflation under control, but it needs to tread carefully. In making the cost of borrowing more expensive today, it risks leaving households paying the price well into retirement.”